Montgomery, Texas
Home loans in Montgomery, from an office on Lake Conroe
Montgomery has a wider range of properties than most towns its size. Lake and golf-course neighborhoods. Custom homes on acreage. Newer communities still filling in. The financing changes with the property, and this page is about what changes and what to have ready.
Dawn Futch works from 18001 Hwy 105 W, Suite 205, on the Montgomery side of Lake Conroe. As a broker she shops a file across a range of lenders instead of one bank’s product line, and in Montgomery that matters more than usual, because the property so often decides which programs are even on the table.
An established Lake Conroe neighborhood and several acres outside town are two different financing conversations, and a growing community is a third. The loan options can move with the property details. So can the appraisal, the insurance, and the monthly payment the buyer actually makes.
The communities, by area, and what each one asks of the financing
Montgomery and Lake Conroe
- Bentwater
- April Sound
- Walden
- Grand Harbor
- Lake Conroe Village
- Pine Lake Cove
- Lone Star Landing
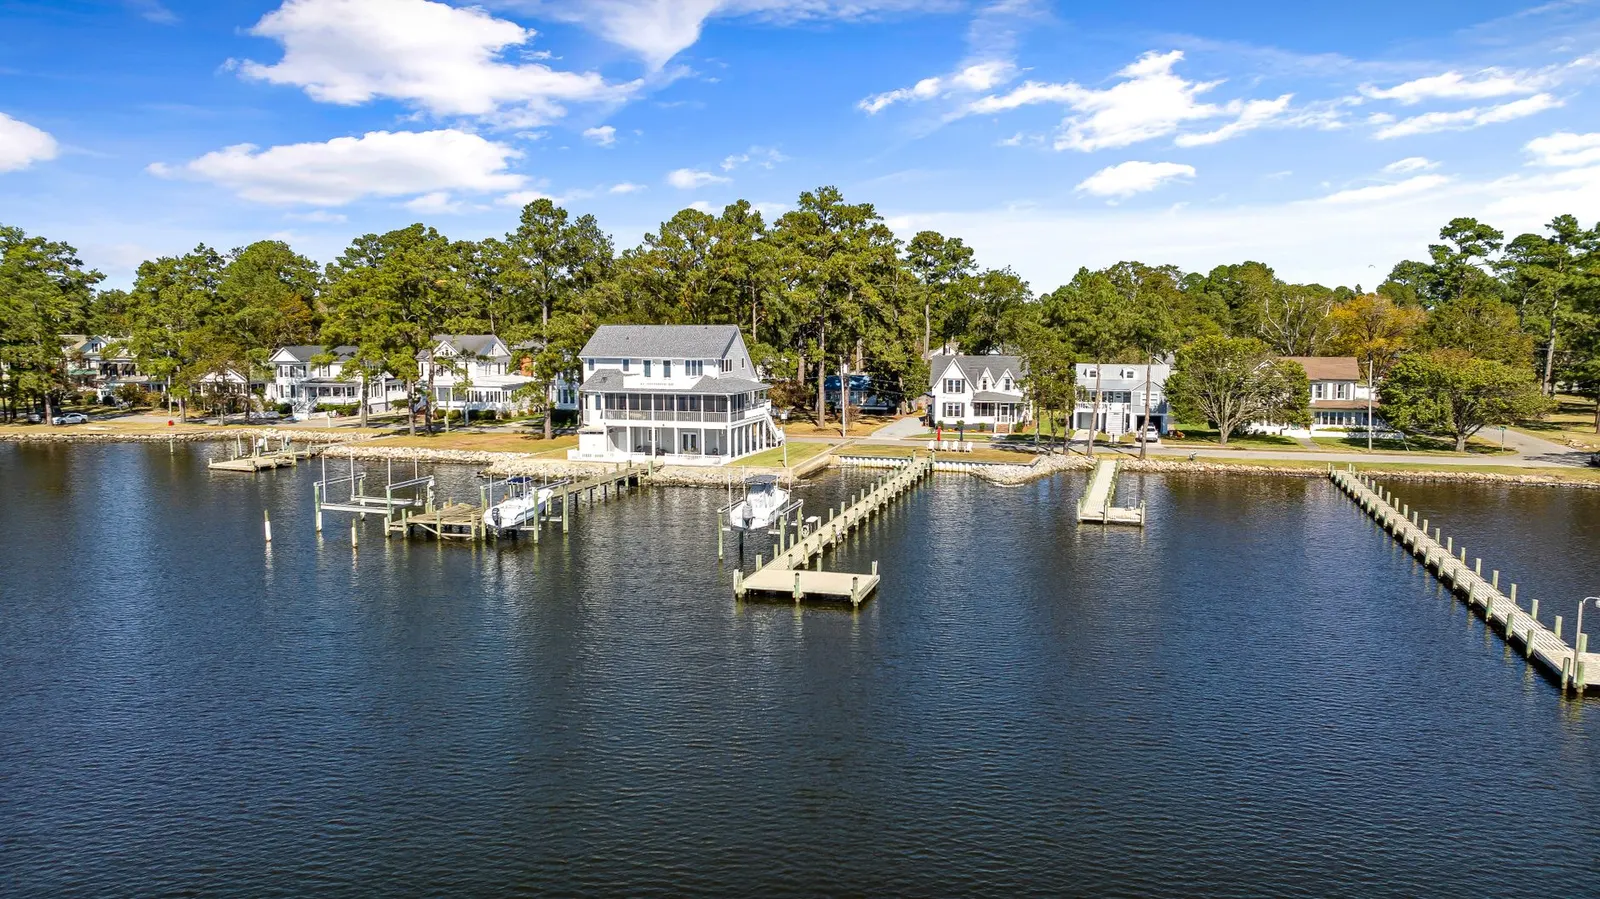
The established lake and golf-course neighborhoods, and the communities in and around town that are still adding homes. Comparable sales are plentiful and appraisals tend to be straightforward. What still needs a close look is the water: flood-zone status first, then whether the home will be a primary residence or a second home, because the requirements differ. Association dues, and in the newer communities MUD or special-district taxes, belong in the monthly number. Where a builder is involved, Dawn’s own words apply: sometimes the builder’s lender incentive is the better overall offer, and sometimes it is worth having her compare the financing before the buyer decides.
Magnolia and Montgomery County
- High Meadow Estates (Montgomery address, Magnolia ISD)
- Montgomery Trace
Acreage and custom-home communities on the Magnolia side of the county. The address may read Montgomery while the schools are Magnolia ISD; both are true, and neither changes the loan. Larger lots and custom builds, often with a private well or a septic system. None of that rules a home out. It does mean the property gets reviewed alongside the buyer, and the sooner those details are on the table the fewer surprises there are before closing.
Nearby Montgomery County communities
- Crown Oaks
- Ridge Lake Shores
- Grand Lake Estates
- Woodforest
Montgomery-addressed communities south and east of town, from custom homes on acreage to an established master-planned community that is still growing. The same questions apply: lot size, wells and septic where they exist, association dues, and the tax rate for that specific community, which can differ noticeably from the one next door.
Five things that change the numbers in Montgomery
These come up on Montgomery files more than anywhere else Dawn works. None of them is automatically a deal-breaker; the property and the loan program each have their own requirements, and that is where the conversation starts. Every one of them is easier handled at the start than at the closing table.
Acreage and custom homes
Dawn finances homes with acreage, not vacant land or commercial property. There is no single acreage limit that applies to every loan. It depends on the home, the land, comparable sales and the lender’s requirements. Properties with more than one residence, unusual outbuildings or income-producing activity may need additional review. Access to multiple lenders is what lets her look for the residential financing option that fits the property.
Wells and septic systems
A private well or septic system does not automatically keep a home from qualifying. Requirements vary by the property, the loan program and the lender. Identifying those systems early leaves room for any testing, inspection, documentation or repairs a program may require.
USDA financing
USDA eligibility is checked by the specific property address. A Montgomery address or a subdivision name does not guarantee that every home in it qualifies. Household income matters too, and USDA may count income from adult household members who are not on the loan. Rather than publish a map that goes stale, Dawn checks the current eligibility for any address a buyer sends her.
Waterfront and second homes
Flood-zone status is specific to each property around Lake Conroe. Flood insurance may be required, and an early insurance quote is how a buyer sees the complete payment instead of a surprise at closing. Requirements also differ between a primary residence and a second home. Condos may need a separate project review, and unique waterfront or custom homes can call for closer appraisal review.
Property taxes, MUD and HOA expenses
Tax rates vary between Montgomery-area communities, so two similarly priced homes can carry very different payments. The seller’s current tax bill is not a safe guide; it may reflect exemptions the buyer will not have or an older value. MUD or special-district taxes, mandatory HOA or POA dues and any special assessments all belong in the full monthly housing cost.
Start with the address
The fastest way to know what applies to a specific Montgomery home is to send Dawn the address or the listing. Flood zone, USDA eligibility, the tax situation, the property type: all of it comes off that one detail, and you do not need a single document in hand to ask. A look at income and credit at the same time is what turns the answer into a real budget.
Not sure what a Montgomery payment looks like with the taxes and dues included? The calculators on the home page let you set the Texas tax situation yourself and see what is included in the estimate and what is not.
Common questions
Does a well or septic system make a home harder to finance in Montgomery?
Not on its own. Requirements vary by property, program and lender, and many Montgomery-area homes on acreage have both. Naming them early is what keeps them from slowing a closing.
Is Montgomery, TX eligible for USDA loans?
Some addresses are and some are not, and it is checked property by property, with household income limits applying as well. Send the address and Dawn checks the current eligibility.
Do Lake Conroe waterfront homes need flood insurance?
It depends on the flood-zone status of that specific property. Where it is required, the premium is part of the monthly payment, so a quote early in the process shows the real number.
Why do two Montgomery homes at the same price have different payments?
Property-tax rates, MUD or special-district taxes, HOA or POA dues and exemptions differ between communities. The seller’s current bill is not always what the next owner pays.
Dawn Futch, NMLS #2090515. Mortgages by Dawn, Montgomery, Texas. Program guidelines and property requirements vary by lender and change over time. Nothing on this page is a commitment to lend.